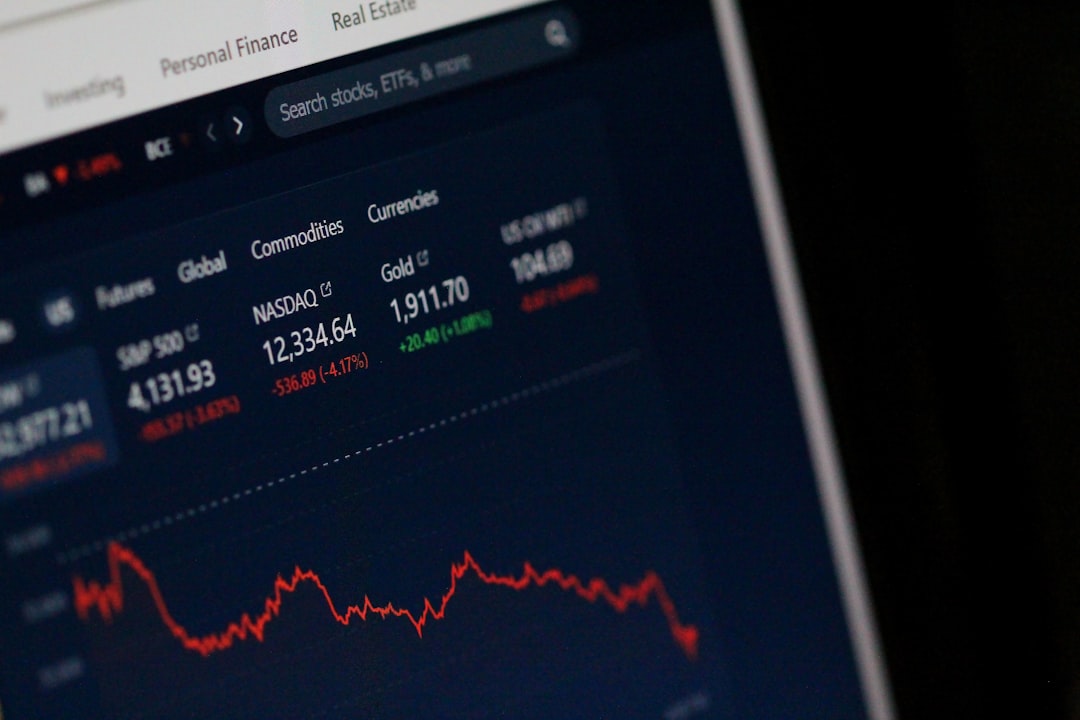
US equities rally on strong corporate results despite headwinds from inflation, geopolitical tensions, and AI-sector valuation worries.
Wall Street's upward trajectory has shown little sign of weakening, with major indices hovering near record levels as companies continue to deliver earnings results that exceed investor expectations. The sustained rally, which has unfolded despite a confluence of macroeconomic and geopolitical challenges, underscores the market's current reliance on corporate profitability as the primary driver of equity valuations in the opening months of the year.
The strength in stock prices stands in contrast to a broader environment marked by persistent inflation concerns, escalating tensions in the Middle East related to Iran, and growing debate within investment circles about whether artificial intelligence-related equities have become overvalued. Yet these headwinds have proven insufficient to derail investor appetite for equities, particularly as companies across multiple sectors demonstrate pricing power and operational efficiency that is translating into bottom-line growth.
Earnings Momentum Sustains Market Confidence
The current market environment is being shaped primarily by the earnings season narrative. As corporations report quarterly and annual results, a pattern has emerged of companies not merely meeting analyst expectations but exceeding them by meaningful margins. This outperformance has reinforced investor confidence that the economic fundamentals underpinning equity valuations remain sound, despite the uncertain backdrop.
Earnings growth has become the market's primary justification for valuations, particularly in a period when bond yields remain elevated and alternative investments offer more attractive returns than they did in the years immediately following the 2008 financial crisis. Companies demonstrating the ability to grow revenues, maintain margins, and return capital to shareholders are being rewarded with share price appreciation, creating a positive feedback loop that has supported the broader market advance.
The breadth of earnings strength across different sectors suggests that the market rally is not narrowly concentrated in a handful of mega-cap technology firms. Instead, companies in consumer discretionary, financial services, healthcare, and industrial sectors have contributed to the overall earnings picture, providing some reassurance to investors concerned about concentration risk in the market.
Inflation Concerns Persist Despite Market Resilience
Elevated inflation remains a significant concern for policymakers, economists, and investors alike. Consumer price pressures, though moderating from the peaks seen in 2021 and 2022, continue to exceed the Federal Reserve's two per cent target, creating uncertainty about the trajectory of interest rates and the potential impact on corporate profitability and consumer spending patterns.
The inflation picture is particularly complex because it creates conflicting signals for equity investors. On one hand, high inflation erodes purchasing power and can squeeze corporate margins if companies cannot raise prices in line with rising input costs. On the other hand, some companies have demonstrated pricing power, successfully passing cost increases on to consumers without materially damaging demand for their products and services.
The Federal Reserve's policy stance remains a critical variable. Markets have been pricing in expectations about when and how aggressively the central bank might adjust interest rates in response to inflation dynamics. The current trajectory of equities suggests that investors believe corporate earnings growth will be sufficient to support valuations even in a higher-for-longer interest rate environment, though this assumption remains subject to revision if economic data shifts unexpectedly.
Geopolitical Tensions and Middle East Dynamics
The escalation of tensions involving Iran and related Middle East conflicts adds another layer of uncertainty to the market backdrop. Such geopolitical developments have historically created volatility in crude oil markets and introduced risk premiums into broader equity valuations, particularly for sectors sensitive to energy costs and global supply chain disruptions.
Crude oil prices have slipped from recent peaks, suggesting that market participants may be assessing the probability and potential magnitude of supply disruptions as manageable within current demand parameters. The energy market's relative stability, despite geopolitical headlines, has helped prevent a more significant drag on equity sentiment. However, this situation remains fluid, and any material escalation in Middle East tensions could quickly reverse the recent decline in oil prices and trigger broader market volatility.
Investors are carefully monitoring developments in the region while maintaining their focus on corporate earnings as the primary driver of equity returns. The apparent market view is that while geopolitical risks warrant attention and may occasionally create short-term volatility, they are not currently seen as existential threats to the earnings growth trajectory that is supporting current valuations.
AI Valuation Concerns and Market Structure
The substantial rally in artificial intelligence-related equities over the past year has prompted growing discussion among market participants about whether valuations in this sector have become disconnected from near-term earnings realities. Some analysts and investors have raised concerns that AI stocks may be pricing in excessively optimistic assumptions about revenue growth and profitability timelines, creating vulnerability to disappointment or shifts in investor sentiment.
These concerns have not substantially dampened investor enthusiasm for technology equities more broadly, but they do reflect a healthy scepticism within markets about the sustainability of extreme valuation multiples. The current market environment appears to be differentiating between companies with proven earnings power and those whose valuations rest more heavily on speculative narratives about future market opportunities.
The debate about AI sector valuations also highlights a broader structural feature of current markets: the concentration of significant portions of major indices' returns in a relatively small number of mega-cap technology and artificial intelligence-related companies. This concentration, while contributing to the headline indices' strong performance, has created dispersion in returns across different market segments and raised questions about the breadth and sustainability of the overall market rally.
Outlook and Market Implications
The resilience of equity markets in the face of multiple headwinds suggests that investors remain convinced that corporate earnings growth will continue to provide sufficient support for valuations. This confidence is not without risk, as it rests on assumptions about the trajectory of inflation, interest rates, consumer spending, and the global macroeconomic environment that could shift relatively quickly.
The coming weeks will be critical as additional companies report earnings, providing fresh data about the strength of corporate profitability and management guidance about future prospects. Any material disappointment in earnings results or forward guidance could trigger a reassessment of valuations, particularly in sectors where multiples have expanded substantially.
The current market configuration—near record levels supported by strong earnings but shadowed by inflation, geopolitical risks, and valuation concerns in specific sectors—reflects a market in transition. Investors are navigating between the positive fundamentals of corporate profitability and a range of potential risks that could alter the trajectory of equities in coming months. The balance between these competing forces will likely determine whether Wall Street can extend its rally to fresh record highs or whether near-term consolidation becomes more probable.