Oil and Natural Gas Corporation's net profit more than doubles in April-June quarter, driven by higher crude valuations and improved realisation rates.
Oil and Natural Gas Corporation (ONGC), India's largest crude oil and natural gas producer, reported a more than doubling of net profit to Rs 17,034 crore in the first quarter of the financial year 2024-25 (April-June), riding on the back of elevated global crude oil prices and improved realisation rates across its portfolio. The exceptional quarterly performance marks a stark turnaround from the previous year's corresponding period, underscoring the cyclical nature of the energy sector and the company's dependence on international commodity price movements.
The surge in profitability comes at a time when crude oil markets have remained volatile yet generally firm, with Brent crude hovering in the range that has favoured producers globally. For ONGC, which operates India's largest oil and gas fields and accounts for a substantial share of the country's domestic hydrocarbon production, the improved pricing environment has translated into stronger bottom-line performance despite production volumes remaining relatively stable.
Revenue Growth Outpaces Cost Pressures
The company's total income rose substantially in the April-June quarter compared to the same period in the preceding financial year, reflecting both the uplift from higher crude realisations and steady production contributions. While the exact composition of revenue growth—attributable to volume increases versus price improvements—has not been fully disaggregated in available disclosures, industry analysts attribute the lion's share of the earnings expansion to favourable commodity pricing rather than production growth.
This revenue trajectory is particularly significant given that ONGC operates in a regulatory environment where domestic crude oil and natural gas prices are subject to pricing mechanisms that, while more liberalised than in the past, still reflect elements of government policy alongside market dynamics. The company's ability to realise higher prices for its crude output underscores the transmission of global market conditions into its earnings, a factor that will remain pivotal to future quarterly performance.
Operating margins have also benefited from the revenue uplift, though the company continues to manage substantial exploration and production costs, field maintenance expenses, and capital deployment across its portfolio of domestic and international assets. The balance between cost control and investment in future production capacity remains a critical management focus area.
Production Volumes Remain Broadly Steady
Despite the doubling of profit, ONGC's oil and gas production in the April-June quarter remained broadly stable, with only marginal declines recorded across certain segments. This relatively flat production profile is noteworthy because it indicates that the earnings growth is driven almost entirely by price realisations rather than volume expansion—a distinction that carries implications for the sustainability of current profit levels as commodity prices fluctuate.
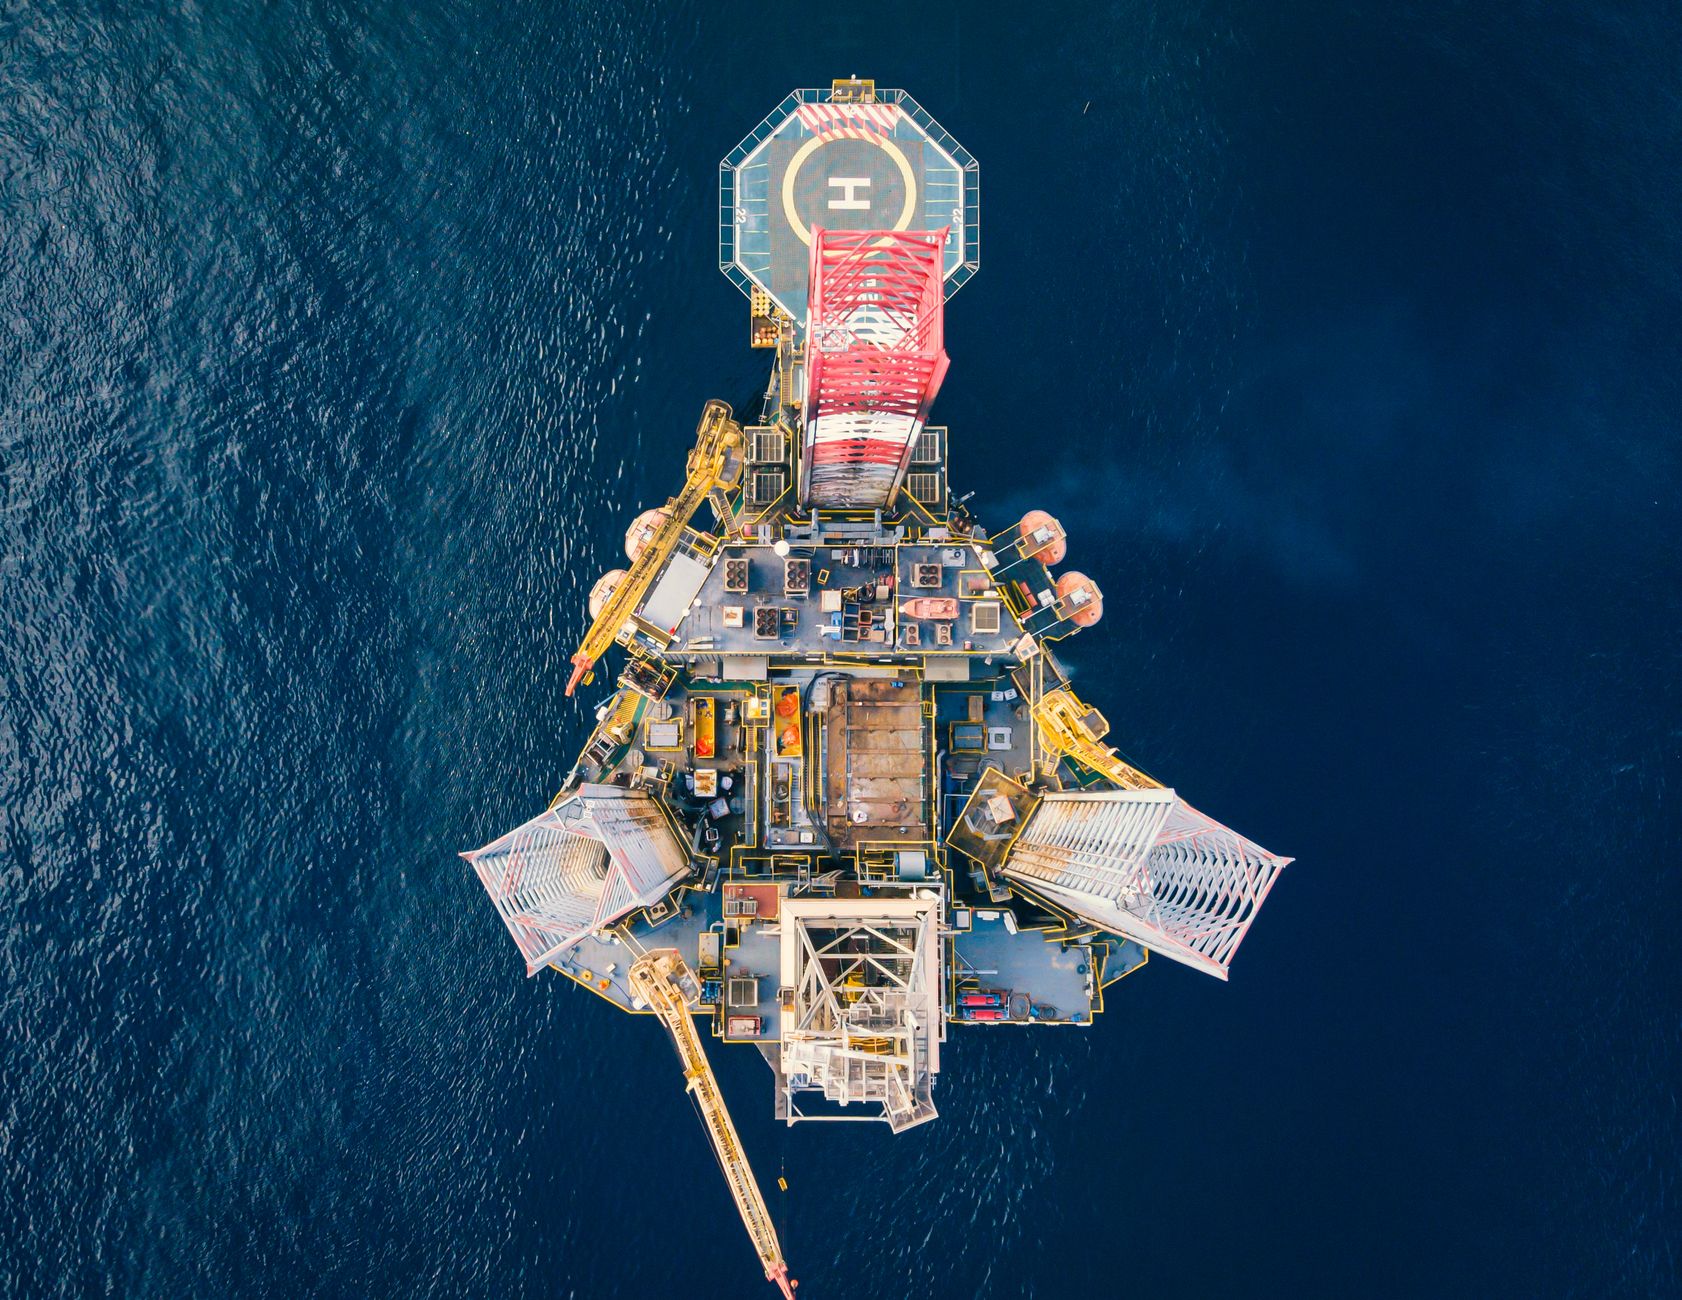
India's domestic crude oil production has faced structural headwinds in recent years, with mature fields in the Western Offshore region experiencing natural production decline curves. ONGC, as the operator of these ageing assets, has had to balance maximising recovery from existing fields against the substantial capital requirements of developing new discoveries and maintaining infrastructure integrity. The marginal production declines reported in Q1 reflect this ongoing challenge, even as the company pursues enhanced oil recovery techniques and field life extension programmes.
Natural gas production, which forms an increasingly important part of ONGC's portfolio given India's energy security concerns and the shift towards cleaner fuels, has similarly remained relatively flat. The company's gas fields, including those in the Krishna-Godavari basin and the Bombay High complex, continue to contribute meaningfully to domestic supply, though they too face typical production decline patterns as reservoirs mature.
The stability of production volumes amid profit doubling illustrates a fundamental reality of the energy industry: in the near term, earnings are often more responsive to price movements than to production changes, particularly for established producers operating mature asset bases. However, this also underscores the importance of ONGC's ongoing capital investment programmes and strategic projects aimed at reversing production decline trends.
Strategic Projects Expected to Drive Future Production
Looking ahead, ONGC management has indicated that several strategic projects in various stages of development are expected to improve future production levels and sustain the company's output growth trajectory. These initiatives span both onshore and offshore domains, with a particular emphasis on deepwater developments and frontier exploration areas.
The company's capital expenditure programme has been calibrated to develop discovered reserves and explore new acreage, particularly in high-potential basins. Major projects under execution include deepwater developments in the Western Offshore that are designed to tap into substantial untapped reserves. Additionally, ONGC is pursuing exploration opportunities in frontier areas including the Bay of Bengal and other prospective regions, though these longer-gestation projects typically require three to five years or more from discovery to production.
The timing of these strategic initiatives is crucial for India's broader energy security objectives. As the country's crude oil imports have remained substantial—currently accounting for roughly 80 per cent of domestic consumption—any expansion in domestic production by ONGC directly reduces import dependence and associated foreign exchange outflows. The government has consistently emphasised the importance of boosting domestic hydrocarbon production, and ONGC's investment plans align with these national priorities.
However, the execution of these projects is contingent on multiple factors, including sustained commodity pricing that justifies capital deployment, regulatory approvals, and the availability of specialised offshore equipment and skilled personnel. Global supply chain considerations and geopolitical factors can also influence project timelines and costs, particularly for deepwater developments that rely on imported technology and expertise.
Market Context and Sector Dynamics
ONGC's Q1 performance must be viewed within the broader context of global energy markets and India's economic trajectory. The current crude oil price environment, while elevated relative to pandemic-era lows, remains within a range that reflects ongoing global economic uncertainty, geopolitical tensions, and the energy transition dynamics affecting long-term demand outlooks.
For ONGC shareholders, the doubling of quarterly profit represents a welcome rebound in earnings, particularly following years when subdued crude prices constrained financial performance. The company's substantial profit generation also strengthens its balance sheet and provides flexibility for dividend distributions, capital investment, and debt management—all critical considerations for a major public sector undertaking.
The company's performance also carries broader implications for India's fiscal position, given that ONGC remains a significant dividend contributor to the exchequer. Higher profits translate into greater dividend payouts to the government, supplementing public finances and supporting government spending priorities.
From an operational perspective, ONGC's stability in production volumes despite commodity price fluctuations reflects the inherent characteristics of established oil and gas operations. Unlike exploration-stage companies whose valuations are driven largely by discovery potential, ONGC's earnings are anchored to a substantial existing production base that generates cash flows across commodity price cycles. This provides revenue stability even as absolute profitability fluctuates with prices.
The company's Q1 results signal that while production growth remains a medium-term challenge requiring sustained capital investment, ONGC's core business continues to generate substantial shareholder value in the current commodity price environment. The realisation of strategic projects over the coming years will be essential for the company to transition from defending production levels to achieving meaningful growth, a shift that would further strengthen India's energy security and ONGC's competitive position within the global energy sector.